 Mekong Monitor
SME Group Urges Lenders to Give Covid-Hit Firms Another Chance at Credit
FASMEC's Te Taing Por is urging lenders to ease penalties and give Covid-affected small businesses a fresh chance to borrow. He also announced financing workshops planned for all 25 provinces and the capital.
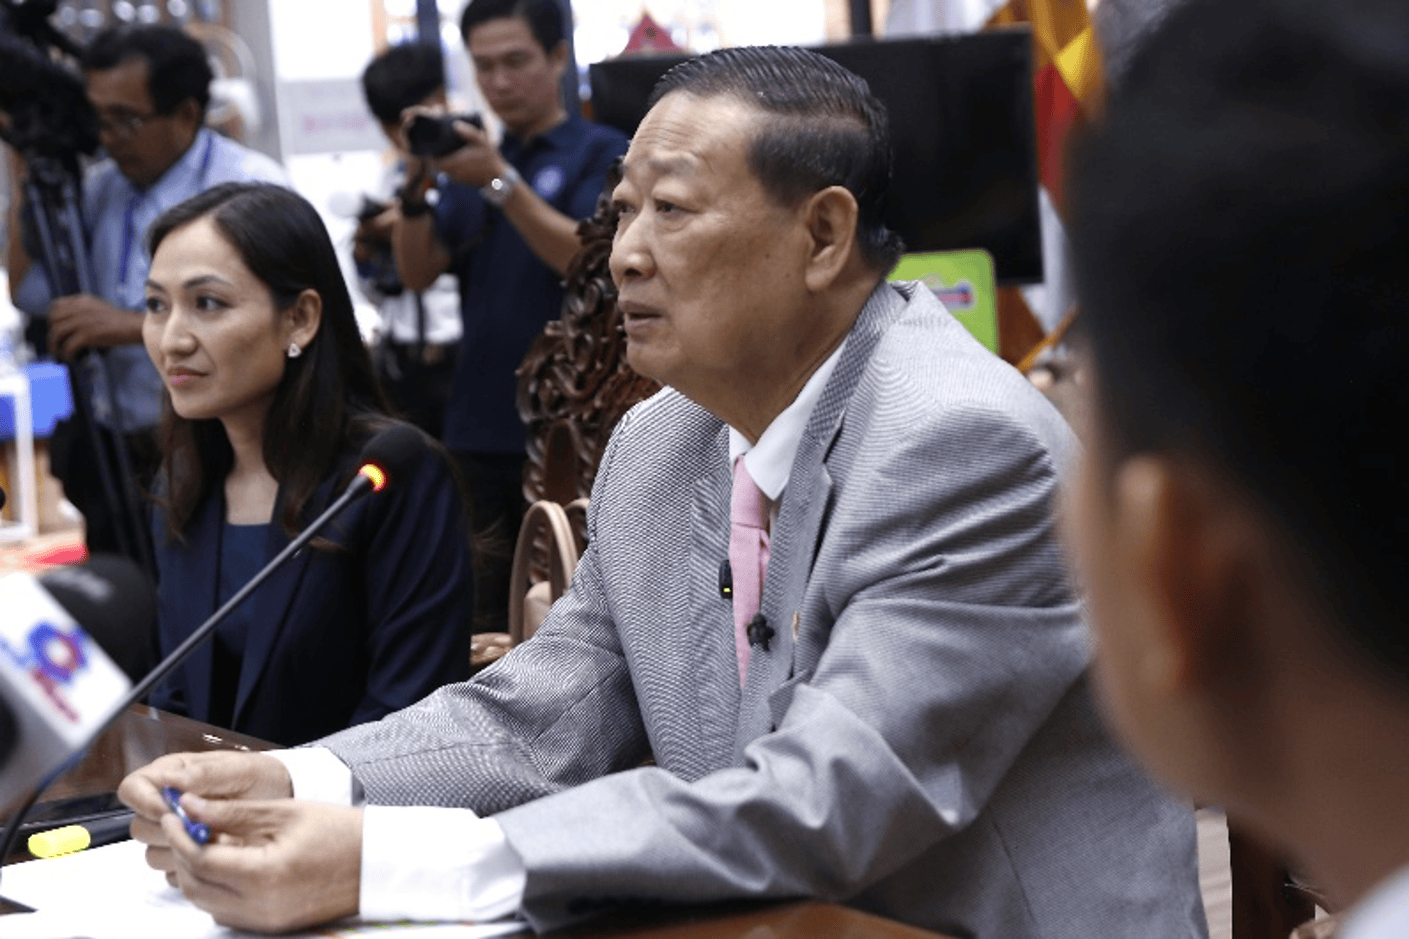
Te Taing Por, head of the Federation of Associations for Small and Medium Enterprises of Cambodia (FASMEC), is asking lenders to take a more understanding view of companies whose loan repayments were disrupted by Covid-19. In his view, these businesses should get a real opportunity to secure fresh funding so they can keep operating and grow.
Speaking at a press conference at FASMEC's headquarters on November 10, Por said some entrepreneurs fell behind on repayments because of a crisis no one could have foreseen. He argued that such setbacks should not permanently block them from the financing they need to rebuild.
He called on lenders to show flexibility toward borrowers with minor credit problems, and to give business owners a way to rebuild trust with their banks.
“If their CBC records show only minor problems, we should consider offering relief and rebuilding trust, so they can borrow again and keep their businesses running,” he said.
Por proposed shortening what he described as a three-year penalty period to three or six months. That would let borrowers show their repayment record has improved and apply for financing much sooner.
He later acknowledged that representatives of the Agricultural and Rural Development Bank (ARDB) and several commercial banks had told earlier forums that a poor report from the Credit Bureau Cambodia (CBC) does not automatically rule out a loan.
Por encouraged business owners facing this problem to bring their individual cases to FASMEC instead of assuming their credit history makes them ineligible. “I will raise these issues directly with the institutions involved. If the National Bank of Cambodia (NBC) is involved, I will take it up with the central bank,” he said.
FASMEC Secretary-General Chhin Ket added that a CBC representative at an earlier forum explained the bureau's role: it supplies banks with information on customers' repayment histories, which banks then weigh when reviewing applications. “CBC is not a barrier to lending. It simply provides information on each customer's repayment history,” he said.
Ket also noted that when a bank declines a loan, the decision may reflect other lending criteria, so it should not be blamed solely on CBC.
Access to capital dominated the discussion, with attendees asking about credit histories, interest rates, application paperwork and eligibility for preferential loans.
One manufacturer at the forum said he had used his house and land title as collateral for an ACLEDA Bank loan at an annual interest rate of about 10 percent. He said these interest costs feed into his production expenses. He also found it hard to prepare the documents needed for lower-interest financing, and admitted he had not yet properly applied for preferential funding.
Por said FASMEC is working with banks and provincial authorities to run financing workshops in all 25 provinces and in the capital. The aim is to help business owners understand lending requirements, prepare their documents and learn about the support available.
He named ARDB, ACLEDA Bank, KB PRASAC Bank and ABA Bank as participants, and said FASMEC's provincial branches can gather information on the difficulties firms are facing.
Asked about interest rates, Por said he could not announce a single rate for SMEs, since terms are set by each lender based on its own assessment of the borrower.
He urged entrepreneurs to use loans only for the production and business development goals they presented to lenders, and to avoid overspending or diverting funds from those plans.
Por said FASMEC will collect cases involving financing difficulties and arrange talks with banks, and it will not charge commissions for facilitating these loans.
“The most important thing is that once you have borrowed, you use the money for its intended business purpose and keep building your creditworthiness,” he stressed.