 Mekong Monitor
Cambodia Relaxes Audit Rules for SMEs While Tightening Oversight of Foreign Branches, Casinos and NGOs
Cambodia's new Prakas 063 raises audit thresholds for many SMEs while extending mandatory audits to foreign branches, casinos and large property developers. Tax specialists also warned of tougher scrutiny of related-party transactions.
Cambodia has introduced new financial reporting rules that may spare many small and medium-sized enterprises (SMEs) from mandatory independent audits. At the same time, the rules widen oversight of foreign company branches, casino operators and large property developers, according to legal and tax professionals.
The changes, set out in Prakas 063 and signed on 18 August 2026, adjust the financial thresholds that determine which companies must have their accounts independently audited. They also introduce new requirements for certain sectors and for non-governmental organisations (NGOs).
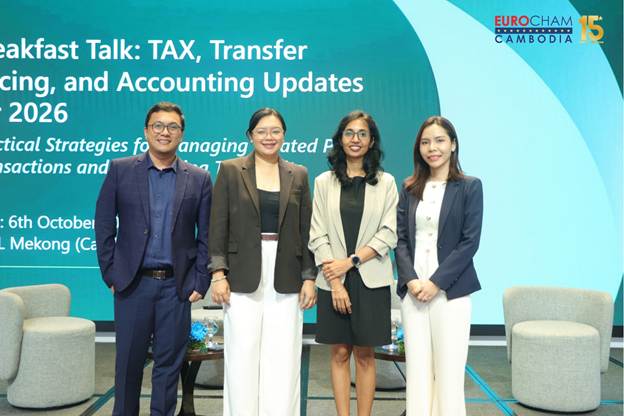
The reforms were discussed at a tax and accounting briefing held on 6 October at the Novotel Phnom Penh. The European Chamber of Commerce in Cambodia (EuroCham) and the legal and tax advisory firm DFDL organised the event.
"This regulation is a major overhaul of Cambodia's financial reporting system, especially regarding which businesses must prepare and submit independently audited accounts," said Michelle Cielo, accounting director at DFDL.
Under the revised rules, the turnover and asset thresholds that trigger a mandatory audit have been raised. For the first time, separate criteria apply to specific sectors.
As a result, many SMEs that previously had to undergo compulsory audits may no longer need to, which could cut their accounting and compliance costs.
However, the framework extends audit obligations to several groups regardless of financial thresholds. These include branches of foreign companies, casino operators and large property developers.
NGOs will face their own requirements, based either on the cost of their projects or on a combination of total spending and staff numbers.
Companies and NGOs that fall outside the new thresholds can apply for an exemption. However, applications must be filed within 30 days after the end of their accounting year, Cielo explained.
She also highlighted tougher penalties for late filing and non-compliance. Unpaid penalties can double after 30 days and triple after 60 days, and further enforcement measures are possible.
The briefing did not disclose the new turnover and asset thresholds or estimate how many businesses will benefit.
The accounting changes come as Cambodia continues to tighten tax administration and scrutiny of corporate financial dealings, particularly transactions between related companies and cross-border arrangements.
DFDL tax partner Vajiravann Chamnan outlined other developments affecting businesses in 2026. These include a 20 per cent capital gains tax on taxable gains from specified capital assets, such as share transfers, investment assets, goodwill and intellectual property. Implementation timelines vary by asset category.
"In general, capital gains tax returns must be filed within three months of the relevant transaction," Chamnan said.
She added that the new provisions clarify who remains liable for unpaid taxes when a business is sold, merged or undergoes a share transfer. The rules set out which entities stay responsible for outstanding tax after a restructuring, including cases where a company did not properly complete deregistration.
Chamnan also noted that the General Department of Taxation (GDT) is focusing closely on transactions between related companies. These include intercompany loans, management fees, sales of goods, and royalty or licensing payments.
If authorities find that such transactions were not properly documented or justified, businesses may lose the right to deduct related-party expenses. They may also face additional tax assessments, penalties of 10 to 40 per cent, and monthly interest. Deliberate tax evasion or fraud can lead to further enforcement action.
DFDL transfer pricing specialist Vandana Vijayakumar discussed Prakas 574, which governs transactions between related parties. She explained that if tax authorities adjust the prices charged between related companies, further tax consequences may follow if the difference is treated as a dividend, loan or capital contribution.
The regulation offers two separate exemption routes. The first removes the full transfer pricing documentation requirement for qualifying businesses that meet certain financial thresholds. The second is a narrower exemption covering some related-party loans.
Vijayakumar stressed that companies must reassess their eligibility for these exemptions each year and should not assume that earlier qualifications still apply.
She advised businesses to document all related-party transactions, review available exemptions regularly, and keep evidence that their dealings follow the arm's length principle. Under this principle, related companies should set terms comparable to those independent businesses would agree.
In a question-and-answer session moderated by DFDL tax partner Diberjohn Balinas, participants raised concerns about the tax treatment of loans and cash advances between parent companies, shareholders and related entities. Others asked how to set appropriate interest rates on intercompany financing and how the new accounting rules would affect businesses that are newly required to be audited.
These concerns reflect the practical challenges companies face in Cambodia's evolving regulatory environment, particularly those involved in cross-border trade or operating through complex corporate structures.
While the revised audit thresholds could lighten the compliance burden for some smaller firms, tougher requirements for certain sectors and closer scrutiny of related-party dealings mean businesses must review their financial reporting and tax practices carefully. Companies preparing year-end accounts and planning their 2026 compliance should first confirm which obligations apply to them.